Returning a Financed Car: How Bad Is the Credit Hit?
15% off on product page · save $1.94
Returning a Financed Car: How Bad Is the Credit Hit?
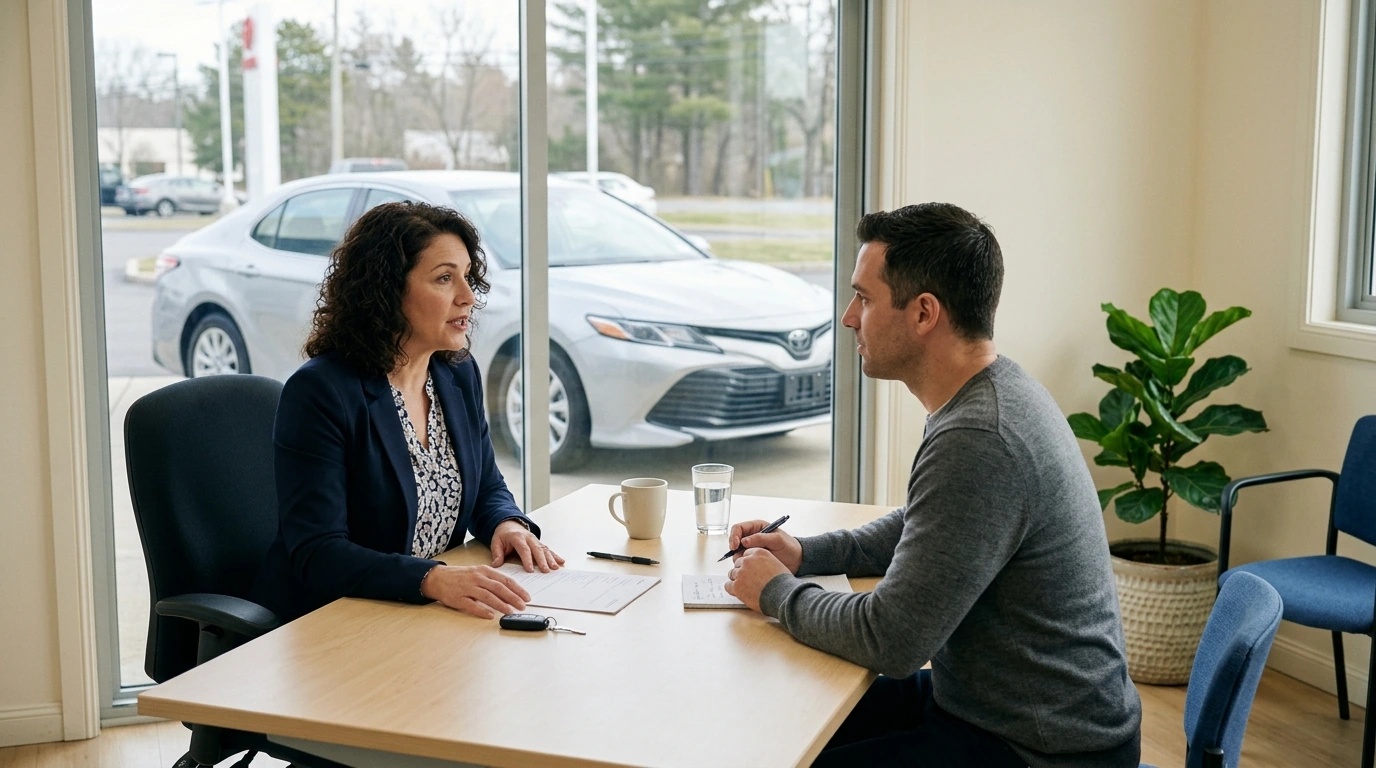
Credit Impact Depends on How the Car Is Returned
Simply handing a financed car back does not cancel the loan. If the lender records the transaction as a voluntary surrender or repossession, the resulting missed payments and derogatory account status can significantly lower your credit score.
There is no universal point reduction, but borrowers with strong credit may experience a drop of 100 points or more. Before returning the vehicle, ask the lender—in writing—how the account will be reported to all three credit bureaus.

Late Payments Can Damage Credit Before Surrender
Auto lenders generally may report a payment once it is at least 30 days late. Additional 60-day and 90-day delinquencies can deepen the damage even before the vehicle is surrendered.
Check your payment history and contact the lender before reaching the 30-day threshold. Request a hardship plan, due-date change, or temporary extension, and confirm whether the arrangement will prevent negative reporting.

Featured in this guide
Selling a Car You Still Owe On: A Step-by-Step Guide to Successfully Selling a Financed Car
Auction Proceeds May Leave a Deficiency Balance
After a voluntary surrender, the lender typically sells the car and applies the proceeds to your loan.
Ask for an itemized post-sale statement and compare the sale price, fees, and remaining principal. An unpaid deficiency may be sent to collections, creating another serious negative entry on your credit reports.
Trade-In or Private Sale May Prevent Surrender
Selling or trading the vehicle can be less damaging when the transaction pays off the loan and the account closes in good standing. First, obtain a 10-day payoff quote and compare it with written purchase offers from several dealers or car-buying services.
If the car is worth less than the payoff, calculate the exact negative equity before signing another loan. Review the step-by-step guide to selling a financed car you still owe on for options and lender coordination.
Negative Records Can Remain for Years
Late payments, repossessions, voluntary surrenders, and related collections can generally remain on credit reports for up to seven years from the applicable delinquency date. Their scoring impact often becomes less severe over time if newer accounts are paid as agreed.
After the transaction, review reports from Equifax, Experian, and TransUnion. Dispute incorrect balances or dates and keep payoff letters, settlement documents, and sale statements.
FAQ
Does giving back a financed car hurt your credit?
Giving back a financed car can seriously hurt your credit if it is reported as a voluntary surrender or repossession. Missed payments, a remaining deficiency balance, and collections can add further damage.
What happens if I return a vehicle I financed?
If you return a vehicle you financed, the lender will usually sell it and apply the proceeds to your balance. You remain responsible for any deficiency and authorized fees unless the lender agrees otherwise in writing.
See if Selling a Car You Still Owe On: A Step-by-Step Guide to Successfully Selling a Financed Car fits your setup



Leave a comment